How to Value a Healthcare Practice: What the EBITDA Multiple Actually Measures
By Gretchen Roberts
What does EBITDA measure and why do healthcare practice buyers use it for valuation?
EBITDA stands for earnings before interest, taxes, depreciation, and amortization. It is the most commonly used valuation metric for healthcare practice acquisitions because it measures the operating cash flow the practice generates before financing and tax decisions, which vary by buyer. A buyer uses EBITDA to determine whether the practice can service acquisition debt, pay a market-rate salary for the incoming practitioner, and still produce a return on the investment. Understanding EBITDA and how the multiple is applied is the foundation of understanding what your practice is worth.
How is EBITDA calculated for a healthcare practice?
Start with net income from the practice's tax return or financial statements. Then add back: interest expense, depreciation and amortization, any owner compensation above or below market rate (normalized to a market salary for the buying practitioner's clinical work), non-recurring expenses, and personal expenses run through the practice.
This adjusted figure is called normalized EBITDA or adjusted EBITDA. It represents the true economic earnings of the practice as a standalone business, separate from the specific owner's financial decisions.
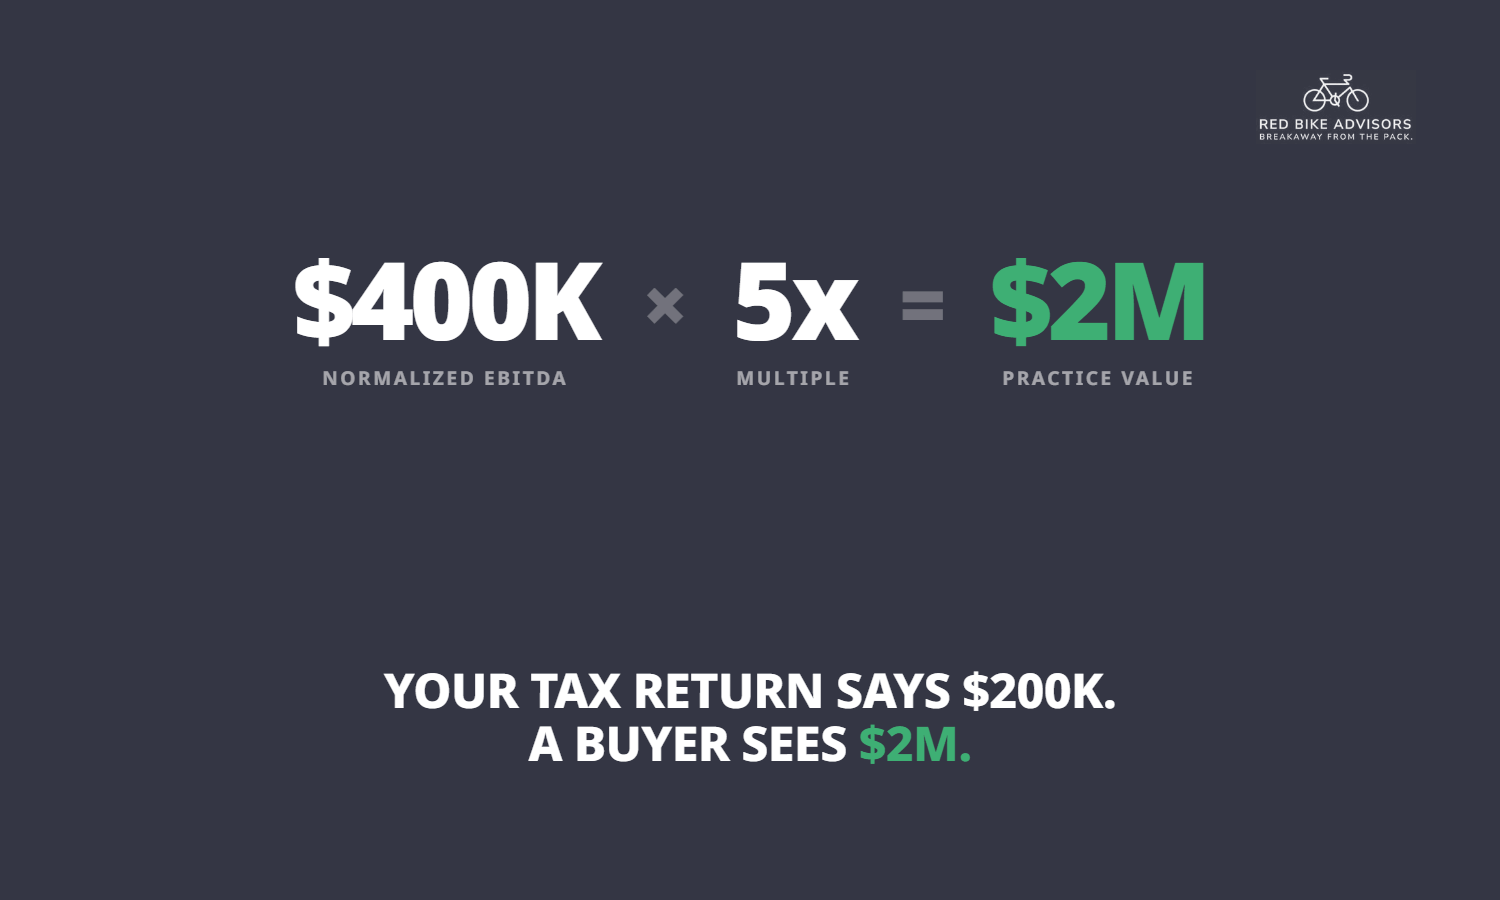
Example: A practice generates $200,000 in net income. The owner pays herself $400,000 in compensation. A market-rate replacement practitioner would cost $200,000. Adding back the $200,000 above-market compensation normalizes EBITDA to $400,000. At a 5x multiple, the practice is valued at $2M, not at the $200,000 net income suggests.
What multiples do healthcare practices typically receive?
EBITDA multiples for healthcare practices vary significantly by specialty, practice size, and buyer type:
- General dental practices: 4x to 6x EBITDA for independent buyers; 6x to 9x for group or DSO buyers
- Chiropractic practices: 3x to 5x EBITDA for most independent transactions
- Physical therapy: 4x to 7x EBITDA depending on payer mix and multi-location potential
- Veterinary practices: 6x to 10x for companion animal practices; 10x to 15x for specialty or emergency practices acquired by PE
- Medical practices: 4x to 8x depending on specialty, revenue cycle, and payor mix
These ranges represent what the market has supported in recent transactions. Individual practice valuations depend on EBITDA margin, owner dependency, growth trajectory, and operational quality.
What is the difference between EBITDA multiple and collections multiple?
Some healthcare practices, particularly dental, are still commonly valued as a percentage of annual collections, typically 60% to 80% for general dental practices. This collectionsbased approach is simpler but less precise.
The EBITDA multiple is more accurate because it accounts for profitability, not just revenue. Two practices with identical collections but different EBITDA margins have very different values. The EBITDA multiple captures that difference; the collections multiple does not.
For practices with strong margins, the EBITDA multiple often produces a higher valuation than the collections percentage. This is why improving EBITDA margin is one of the highest-leverage value-building strategies available to a practice owner.
What reduces the EBITDA multiple a buyer applies?
Buyers apply a risk premium to uncertain practices and a risk discount to practices with concentration risks. Factors that reduce the multiple:
- High owner dependency (seller generates more than 55% to 60% of production)
- Declining revenue trend in the prior two years
- Disorganized or inconsistent financial records
- Short remaining lease term without renewal options
- High staff turnover
- Limited patient base or concentration in a single referral source
The most important insight about EBITDA valuation
EBITDA multiple valuation means that every dollar of sustained EBITDA improvement generates multiple dollars of enterprise value. A practice owner who increases EBITDA by $50,000 through overhead reduction and compensation optimization does not just increase their income by $50,000 that year. They increase their practice value by $200,000 to $300,000 at a 4x to 6x multiple.
That is a compelling return on the financial work that happens before an exit.
A free strategy session is the right place to understand how your practice's EBITDA and valuation stack up: https://redbikeadvisors.com/book-a-free-strategy-session
Gretchen Roberts
Gretchen Roberts is CEO of Red Bike Advisors LLC. As a business owner herself, Gretchen has a deep understanding of the problems, questions, and financial pain points that business owners experience on a daily basis, and how strategic financial and tax planning is the key to "breakaway" business growth and success.